
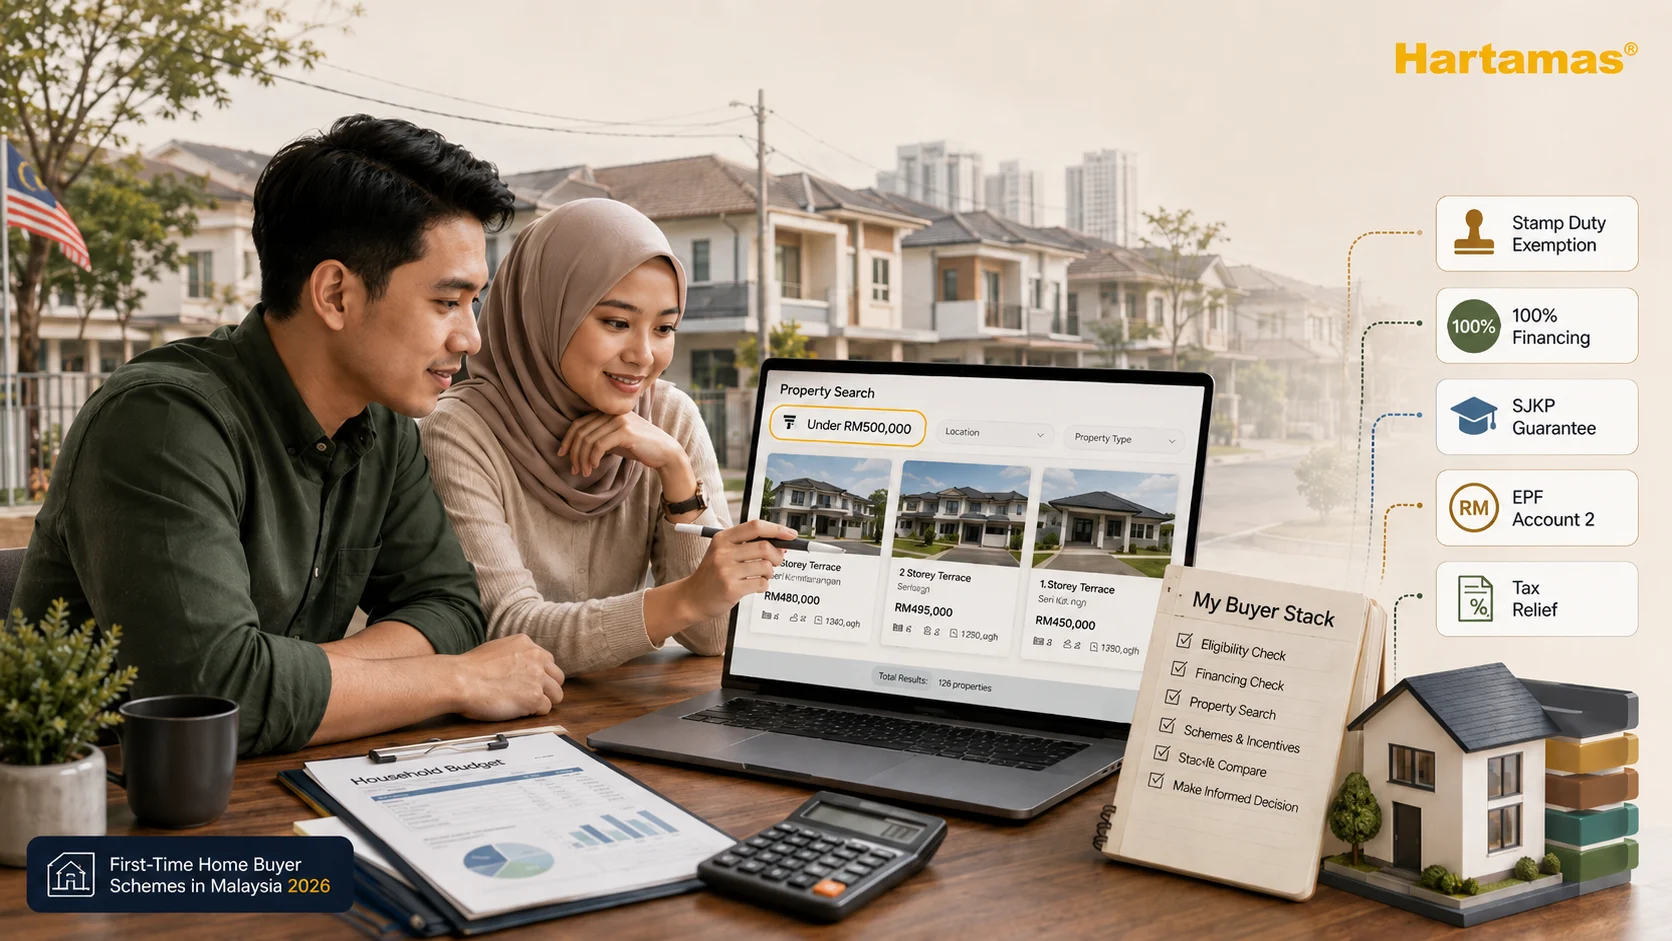
Stepping into the Malaysian property market in 2026 offers exciting opportunities alongside unique financial challenges. Government initiatives can significantly ease your entry by lowering upfront costs, providing loan guarantees, or granting access to subsidised residential projects.
Securing the right assistance requires careful preparation before making any financial commitment. Matching your household income, employment profile, and target location with the right scheme ensures a smoother path to homeownership.
Understanding the exact requirements of each initiative protects your hard-earned savings. Evaluating these programmes early allows you to build a realistic budget and avoid unexpected hurdles.
Which Government Schemes Can Reduce Your First-Home Costs?
Several nationwide and state-level initiatives aim to make homeownership accessible. Depending on your eligibility, these programmes can reduce transaction fees or provide competitive financing options.
Stamp Duty Exemption for Eligible First-Time Buyers
Malaysian first-time buyers can benefit from a full stamp duty exemption on transfer instruments and loan agreements. This relief applies to qualifying residential properties priced up to RM500,000 under the current initiative running until 31 December 2027.
This exemption can save you thousands of ringgit in upfront transaction costs. Always verify your eligibility and property status with a conveyancing lawyer before executing formal agreements.
Even with stamp duty relief, you must budget for legal fees, valuation, insurance, and moving expenses. Preparing for these ancillary costs ensures complete financial readiness.
SJKP and Financing Support Programmes
The Housing Credit Guarantee Scheme (SJKP) assists buyers who lack standard proof of fixed income. It provides government-backed guarantees to help gig workers, freelancers, and small business owners secure bank financing.
Participating lenders evaluate your repayment capacity based on alternative income evidence. Keeping organised records of tax filings, bank statements, and business transactions improves your approval chances.
Remember that a guarantee acts as credit support for the bank, not a repayment subsidy. You remain fully responsible for servicing your monthly loan instalments on time.
Affordable Housing: PR1MA, Residensi Wilayah, and State Programmes
PR1MA develops quality, affordable homes for middle-income Malaysians across urban and suburban areas. Allocations depend on project availability, income thresholds, and specific eligibility criteria.
Residensi Wilayah delivers affordable residential units specifically across the Federal Territories. State-level programmes like Rumah Selangorku and Rumah Mampu Milik Johor provide targeted housing options under distinct local rules.
Examine project location, daily transport links, maintenance fees, and minimum holding periods before committing. Subsidised housing often includes strict resale restrictions that affect future property plans.
LPPSA Financing for Civil Servants
Public sector employees can access dedicated financing facilities through Lembaga Pembiayaan Perumahan Sektor Awam (LPPSA). This scheme offers competitive financing terms tailored to civil servants.
Your eligible borrowing limit depends on your basic salary, scheme of service, and existing deductions. Always confirm your exact entitlement before signing a property booking form.
How Do You Choose the Right Scheme for Your Situation?
Choosing the best housing scheme involves balancing your financial capacity with your lifestyle needs. A project with a lower purchase price may not be ideal if travel expenses strain your monthly budget.
Start by verifying income limits and location criteria for each programme. Comparing these parameters helps narrow your choices to the most practical options.
Match Income Limits, Property Prices, and Location Rules
Review whether a programme calculates limits using individual salary or combined household earnings. Certain initiatives also require applicants to reside or work within specific state boundaries.
Check property price caps and ownership restrictions carefully. Confirm all criteria through official agency portals rather than relying solely on marketing materials.
What Self-Employed and Gig Workers Should Prepare
Self-employed applicants must build a clean and consistent financial profile before applying for financing. Lenders will inspect bank statements, EPF contributions, tax declarations, and commercial contracts.
Separate personal and business finances to demonstrate clear cash flow patterns. Settling outstanding tax filings early prevents unnecessary processing delays with financial institutions.
Budgeting for Cash Needs Beyond the Down Payment
Buying a home requires liquidity beyond the standard deposit. You must allocate cash for utility connections, renovation work, furnishing, and initial maintenance charges.
Request an itemised breakdown of legal and documentation costs from your solicitor. Maintaining a dedicated emergency reserve protects you against unexpected expenses during the handover period.
Confirm Loan Eligibility Before Paying a Booking Fee
Seek preliminary financing assessments from multiple banks before signing documents. Review your CCRIS report beforehand to ensure all credit records are accurate and up to date.
Ensure any booking agreement includes a clear refund clause if your loan application is unsuccessful. A cautious approach safeguards your initial deposit while finalizing financing arrangements.
Making a Confident First-Home Decision
Purchasing your first residential property in Malaysia becomes manageable with structured planning and thorough research. Leveraging relevant government incentives can significantly lower your entry barrier.
Take time to verify property titles, tenure conditions, and all associated costs. Conducting diligent assessments allows you to secure an affordable home that fits your long-term goals.
